As business energy consultants, we are constantly on the lookout for the finest deals on the market for our clients, and we work tirelessly to achieve these. Our monthly market reports provide views directly from our specialists. Use our price analysis, market signals, and political changes to help you make the right choice when it comes to energy decisions.
Download PDFDisclaimer: The information contained in this document has been prepared in good faith by Ginger Energy and provides our views on current/future trends and outcomes, but, as with all forecasts dependent upon multiple, complex variables, there is no certainty whatsoever that our forecasts will turn out to be correct. The information may be based on licenced 3rd party data, publicly available sources, assumptions, and observable market conditions and may change without notice. No warranty, express or implied, is made as to the accuracy, correctness, fitness for purpose, completeness or adequacy of this information nor is it intended to serve as basis for any procurement decision and as such Ginger Energy shall not accept any responsibility or liability for any action taken, financial or otherwise, as a result of this information. Please note that this email is intended for the recipient only and may not be copied, reproduced, or distributed without the prior consent of Ginger Energy.
Market Context
Gas and power prices rose by around 30–40% in October
- Front-season gas (Summer 27): +41% month-on-month, end of October versus end of September.
- Front-season power (Summer 27): +32% month-on-month, end of October versus end of September.
- EU gas storage: around 75% full in late October, approximately 3.5 percentage points higher than at the end of September, but around 15 points below the five-year average.
UK front-season gas and power prices rose by around 30–40% in October. Restricted Middle Eastern LNG supplies, low European storage and colder forecasts increased concern about winter availability. Prices initially held relatively steady, then climbed through much of the month, with brief falls on diplomatic headlines. The European benchmark gas price (TTF) passed €100/MWh on 30 October, its highest level since December 2022. Stronger Norwegian supply and improving US LNG exports provided some relief, but did not remove supply concerns. Annual gas and power prices for delivery from April 2027 rose by around 30–40%.
Winter supply concerns kept future prices high
Steady opening, then increases
Early October trading was comparatively steady. Prices subsequently climbed as the approaching heating season increased attention on Europe's limited protection against supply setbacks.
Shipping and production concerns
Continuing disruption around the Strait of Hormuz, the key Gulf shipping route for oil and LNG, and reported Qatari production damage increased supply concerns (see the conflict update).
Colder forecasts increased demand expectations
Cooler forecasts raised expected heating demand through the month. Asian buyers also sought replacement LNG, increasing competition for cargoes available to Europe.
Supply improvements offered some relief
Higher Norwegian production and improving US LNG exports helped Europe's supply position. Better nuclear availability and weaker industrial consumption also reduced expected gas requirements.
Storage remained below normal
By late October, EU gas storage was around 75% full, about 15 points below the five-year average. That leaves less cushion against cold weather or supply disruption.
In Other News
On 14 October, the European Commission proposed delaying methane monitoring and reporting requirements for imported oil and gas by one year, from January 2027 to 2028. Importers would have until 31 May 2029 to demonstrate that the previous year's imports met equivalent monitoring and reporting standards. The proposal could ease a potential compliance barrier for LNG imports, particularly from the US. It delays implementation rather than removes methane controls, and does not itself increase production.
Seasonal Prices
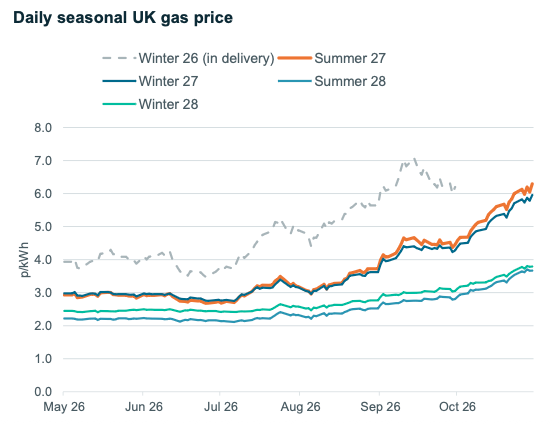
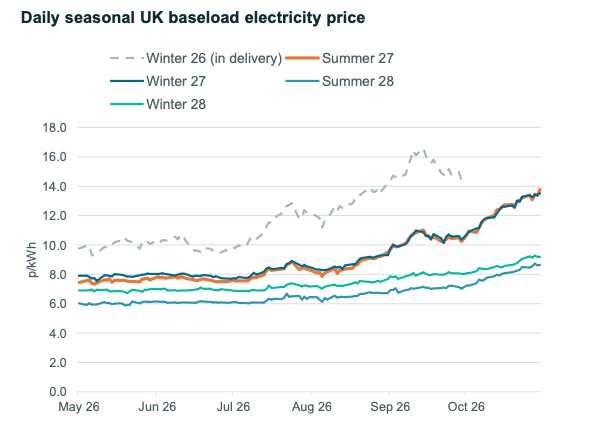
Seasonal gas and power prices rose by around 20–40%
Price Table
Front-month gas and power rose by over 40%
Front-month gas and power prices rose by 43% and 44% respectively, showing the strongest increases among near-term products. Spot gas rose by 13%, while spot power increased by 10%. Front-season gas and power prices rose by around 30–40%, while annual prices from April 2027 rose by around 30–40%. Gas and power moved together across spot and front-month products as winter supply concerns grew.
Energy-Only Prices
| Product | Fuel | Oct-26 (p/kWh) | Sep-26 (p/kWh) | Month-on-Month Difference |
|---|---|---|---|---|
| Spot prices (month average) | Gas (NBP) | 7.20 | 6.38 | ▲ 13% |
| Spot prices (month average) | Power (UK baseload) | 14.80 | 13.50 | ▲ 10% |
| Front month (month close) | Gas (NBP) | 8.69 | 6.10 | ▲ 43% |
| Front month (month close) | Power (UK baseload) | 20.38 | 14.11 | ▲ 44% |
| Front season (month close) | Gas (NBP) | 6.29 | 4.45† | ▲ 41% |
| Front season (month close) | Power (UK baseload) | 13.77 | 10.42† | ▲ 32% |
| Apr-27 annual price (month close) | Gas (NBP) | 6.06 | 4.33† | ▲ 40% |
| Apr-27 annual price (month close) | Power (UK baseload) | 13.64 | 10.48† | ▲ 30% |
†Same contract as this month (Summer 27 and the April 2027 annual price), so these differ from last month’s report, which showed Winter 26 and the previous annual price.
Fully Delivered Annual Energy Unit Rates (p/kWh)
Approximate average prices for 12 months from April 2027: Electricity 30.69p/kWh; Gas 7.26p/kWh.
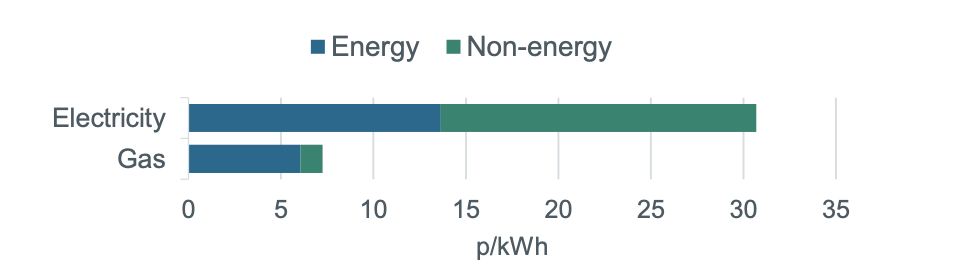
Quoted figures are approximate average prices for 12 months from April 2027 and do not include supplier risk premiums. Actual prices vary depending on customer, meter type, size, location and contract duration.
Wider Historical Context
Prices remain far below the 2022 peak
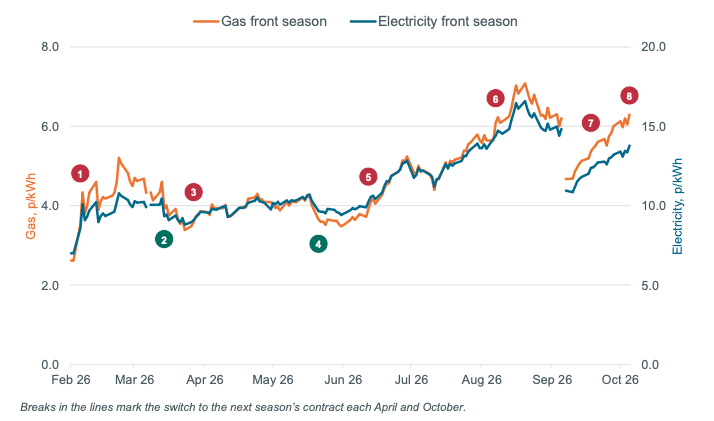
Breaks in the lines mark the switch to the next season’s contract each April and October.
Outlook
Lasting price falls need more reliable supply
Winter temperatures, storage withdrawals and reliable LNG arrivals are likely to determine how much pressure remains on prices for future delivery. A durable diplomatic agreement and safer Gulf shipping could reduce supply concerns, but restoring damaged facilities and suspended deliveries would take longer. Norwegian production, US export availability and Asian demand are likely to shape Europe's access to replacement cargoes. Mild, windy conditions and reliable nuclear generation would preserve storage. A prolonged cold spell or major supply outage would increase winter costs and leave more gas to replace during the following summer.
Bullish Signals Could Push Prices Up
- A prolonged cold spell would accelerate withdrawals from already low European storage.
- Renewed military action or shipping disruption would threaten LNG delivery reliability.
- Stronger Asian demand would increase competition for replacement LNG cargoes.
Bearish Signals Could Bring Prices Down
- A credible agreement restoring safe Gulf shipping would ease concern about supply availability.
- Reliable Norwegian production and stronger US LNG exports would improve Europe's supply position.
- Mild, windy weather and dependable nuclear generation would reduce gas use and preserve storage.
Middle East Conflict Update
A closer look at the conflict and how it is affecting UK gas and power prices.
Qatari LNG suspensions extended through December
Supply Scorecard
| Area | Status at Month-End | Change Since Last Month |
|---|---|---|
| Strait of Hormuz shipping | Repeated tanker attacks; some LNG ships passed, but traffic remained heavily restricted | No change |
| LNG supply | Qatari suspensions extended to December; production damage remained a concern | Deteriorating |
| Hostilities | Saudi–Houthi fighting continued; renewed US action remained a risk | No change |
| Diplomatic talks | Mediation continued without agreement on safe passage or wider terms | No change |
What Changed This Month
- Reports described damage to Ras Laffan, Qatar's main LNG export site, with repairs to some equipment expected to take several years.
- Qatari delivery suspensions extended through December for several buyers. Eighteen laden LNG vessels reportedly left the Gulf during 1–26 October.
- Iran and Oman discussed temporary safe-passage arrangements, while Qatari mediation continued. No agreement restoring normal commercial shipping was confirmed.
Signposts to Watch
- A confirmed safe-passage agreement followed by sustained increases in commercial shipping.
- Resumed Qatari deliveries and a verified timetable for repairs to damaged production equipment.
- Whether US–Iran diplomacy advances or military action resumes after November's US midterm elections.
Price Movements Since the War Began
Front-season prices have tracked each turn in the conflict
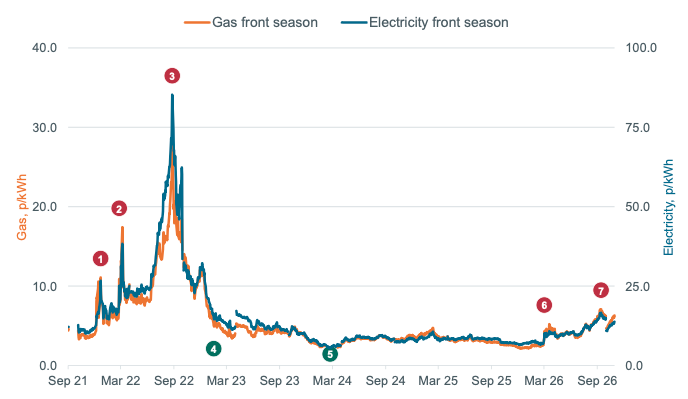
Breaks in the lines mark the switch to the next season’s contract each April and October.
Want the best energy and water contracts for your business?
Get in touch today to start saving money and time spent on finding the best business energy deals.